From boom to brake: Property under pressure

How are geopolitics and energy shocks shifting risk in Australia’s property and private credit markets? Paul Miron argues the latest pressures are already biting – from construction costs that could jump 20% to clearance rates in Sydney slipping toward 50%. Paul outlines why he believes some property prices have already fallen more than 10%, why lenders need to interrogate valuations more aggressively, and why secured private credit over established property remains his preferred position in volatile conditions. He also weighs in on potential tax changes – negative gearing, CGT and GST – warning that poorly timed reforms could tighten supply further and push rents higher, echoing the policy reversal of 1985.

Key points:

  • Energy shock and supply chain issues seen driving construction costs higher
  • Clearance rates and sentiment viewed as signalling property price falls already under way
  • Secured private credit over established property preferred to construction and corporate debt
  • Proposed changes to negative gearing and property tax seen as risking reduced supply and higher rents

Disclaimer:

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. The information provided is general in nature and reflects the views of the speaker at the time of recording. Forward-looking information is inherently uncertain, and actual results may differ materially from projections. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice.

Our prosperity now depends on decisions politicians hate making

Msquared Capital’s Paul Miron says Australia’s economic prosperity has been built on good luck and not good policy. In an exclusive interview with Livewire’s James Marlay, Paul explores the supply and demand dynamics plaguing property markets and the broader economy. They also talk about the run of redemptions hitting high profile global private credit funds.

Written by James Marlay for Livewire Markets

Front pages today are dominated by headlines about the war in Iran. Hopefully, there’s a resolution soon. The risk is that any escalation adds to the already entrenched challenges facing Australian households and the domestic economy.

Rising inflation and cost-of-living pressures were already biting. Layer in structural issues like housing affordability, and the picture becomes more complicated. Higher input costs are likely to flow through the economy, adding further pressure where it’s already being felt.

In a recent Livewire article, Msquared Capital’s Paul Miron put the spotlight on the structural challenges confronting current and future governments.

Put simply, Miron argues Australia’s economic track record owes more to luck than good policy. Years of strong growth, particularly in property prices, have masked deeper structural weaknesses.

Australia is currently the only G12 economy to have resumed tightening monetary policy amid persistent inflation, a signal that the underlying pressures are deeper than many care to admit – Paul Miron

To an extent, this is familiar territory. Housing affordability is well documented. So too are weak productivity growth and rising levels of debt-funded government spending.

Where it gets more contentious is how to fix it. Miron’s view is that supply and demand need time to rebalance the economy. That means difficult decisions, particularly around migration settings and government spending.

Long-term structural change will come from very brave politicians – Paul Miron

What won’t work, in his view, is trying to stimulate demand in an already constrained housing market through subsidies, or discouraging investment via policies targeting property investors.

Instead, Miron outlines a series of measures aimed at restoring balance between supply and demand, which he believes is the key to easing pressure on property prices.

Given the vibrant discussion that took place in the comments on Paul’s article I reached out to him to discuss his position further. I also took the opportunity to ask him about the implications of the run on redemptions hitting a number of high profile global private credit funds for local investors.

Topics discussed

  • 0:00 – Australia’s economic Ponzi Scheme
  • 2:35 – Housing affordability – stuck between a rock and a hard place
  • 8:55 – Policy solutions require brave politicians
  • 10:57 – Why isn’t new housing affordable?
  • 13:59 – Implications of the recent redemptions in private credit funds
  • 18:46 – Australian private credit is has a point of difference
  • 21:32 – ASIC review a net positive for Australian private credit


Disclaimer

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. Information contained in this article is general in nature and has been prepared without taking into account your objectives, financial situation or needs. It does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice. Property and private credit investments carry risks, including market downturns and borrower defaults, and neither past performance nor security over property guarantees future returns or capital protection.

Brokers to claim higher share of commercial lending market amid industry diversification

Brokers are handling increasingly complex scenarios across both traditional and alternative lending avenues.

Written by William Farrington – Mortgage Professional Australia

Commercial broking is, in many ways, still in its infancy.

While broker share in the residential mortgages space has seen breakneck growth – having climbed from – to nearly 80% today, brokers’ commercial market share still sits at roughly 35% to 40%, depending on who you ask.

But as the broking industry matures, many experts expect this number to shoot up in the coming years.

Michael Volkiene, general manager, loan origination and credit, of private credit group Msquared Capital, expects brokers to claim 55%-60% of the commercial lending space over the next three years.

He sees this as a result of brokers diversifying and responding to the increasingly sophisticated needs and expectations of their clients.

Private credit, he argues, is on a similar trajectory.

“In the US, close to 50% is written in private. In Europe it’s around 40%. In Australia, you probably sit between 9% and 12% at the moment,” notes Volkiene. He sees the “natural” level here moving to around 22%-25% over the same period.

Volkiene believes abundant dry powder, banks retreating from complex scenarios, and the rise of specialist non‑bank players are all helping private credit gain ground.

“Brokers are seeing some challenges with the traditional lenders,” he says, pointing to bottlenecks around SLAs, shifting appetite and confidence.

Msquared operates predominantly in the three‑ to 36‑month space, funding non‑regulated commercial deals such as bridging, residual stock and cash‑out facilities.

But while the likes of Msquared tout the benefits of the unregulated commercial lending space, sentiment is clearly bullish among the traditional players too.

Speaking on NAB’s latest commercial broker economic update, executive of commercial broker Chris Thomas highlighted “significant levels of system growth for business lending, much higher than in previous years”, noting that businesses are clearly prepared to borrow despite higher interest rates.

During the update, NAB chief economist Sally Auld said internal data shows much of the uplift is concentrated in property and agriculture, with a particularly strong appetite for the purchase of commercial buildings rather than just land or residential stock.

That pattern, she argued, signals businesses are making longer‑term bets on income‑producing assets and regional growth rather than simply chasing short‑term gains.

Auld also pointed to NAB’s business survey, which shows most firms that want credit still report it is “pretty easy” to obtain, suggesting banks remain keen to lend and current rate levels are not yet biting hard enough to choke off investment demand (although this was said prior to the March RBA rate hike).

NAB gained market share in both small-to-medium enterprise and total business lending in 2025, per its latest set of results.

Big Four competitor Westpac has also enjoyed growth in business lending. Following a concerted effort by management to target the commercial space, interim results published last September showed a 14% year-on-year growth in the segment.

Brokers urged to diversify

Brokers can no longer afford to be “resi‑only” players, says Volkiene, who sees diversification into commercial as both inevitable and accelerating.

He says brokers want to provide “cradle to grave” solutions for clients, supporting them as they move between residential, business and investment needs.

“Commercial lending is relationship driven and technically complex,” says Volkiene.

“Experience matters – from understanding diverse income streams and non‑standard documentation, to taking a commercial approach to valuations.”

Volkiene reckons commercial expertise gives brokers a way to deepen their client relationships and grow their businesses. Others in the broking industry thoroughly agree.

In ongoing roadshows across Australia and New Zealand, Simon Bednar, chief executive of mortgage aggregator Finsure, has been stressing the importance of diversification, especially in response to the Middle East crisis that is causing havoc on fuel prices and consumer confidence.

“We are all facing challenging times with interest rate increases and market fluctuations outside of our control. It’s important for brokers to be prepared to diversify their service offering and revenue streams in response to these events,” Bednar told brokers.

He continued: “This will enable brokers to offset the negative impact of rate rises and better protect their businesses from unpredictable outside forces. Our industry is increasingly moving towards a more professional approach which helps develop more loyal clients during difficult times.”

Finsure saw a 43% surge in commercial and asset finance lending in its latest financial year.

“We are seeing more and more brokers moving into diversified lending – particularly commercial – as they look to expand their revenue in this competitive environment,” said Bednar.

Mortgage aggregators crack into commercial

Finsure is not the only mortgage broking group to see similar trends.

Connective recently powered up its commercial lending offering by adding ORDE Financial, Pallas Capital and Msquared Capital to its lender panel.

Brent Starrenburg, head of commercial and asset finance at Connective, is seeing brokers navigate increasingly complex commercial lending scenarios.

Additions like Msquared to Connective’s lender panel to flesh out the options available to brokers handling these complex scenarios.

“Msquared Capital brings strong commercial experience and a practical credit approach, particularly for more complex property transactions,” says Starrenburg.

“That gives our brokers confidence they can deliver when traditional options fall short.”

LMG, Australia’s largest mortgage aggregator, has also made an aggressive push into commercial broking.

“The average person is going to have financial needs beyond just a mortgage… What we’re seeing is good brokers want to say to their customer, ‘I’m your destination for all your financial needs, whether that’s a car loan or if you want to buy a factory,” LMG group executive of commercial finance Stephen Scahill told MPA at last year’s LMG Growth Summit.

“It’s about convenience for customers, but for brokers it’s also about securing your own network,” said Scahill.

Disclaimer:

General information only and does not constitute financial, investment, or legal advice. Msquared Capital’s lending activities are limited to writing loans for business and/or investment purposes only. The consumer protections in the National Credit Code do not apply.

The flight to quality in Australian private credit

Despite weak consumer confidence and geopolitical uncertainty, Australian borrowers with strong balance sheets are re‑gearing to capture business opportunities. Msquared Capital’s General Manager Loan Origination & Credit Michael Volkiene tells ausbiz that rising interest rates have not subdued the impact investor demand for yield has on lenders, where the contest for quality borrowers is intensifying. He expects continued strong growth in activity from entrepreneurial Australian SMEs for the remainder of the year.

Key points:

  • Rising competition and a flight to quality in Australian private credit
  • Rate hikes seen as expanding the opportunity set for non‑bank and private lenders
  • Market viewed as maturing towards higher private credit penetration over coming years
  • Private credit framed as a portfolio component where risks and liquidity are well understood

Disclaimer:

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. The information provided is general in nature and reflects the views of the speaker at the time of recording. Forward-looking information is inherently uncertain, and actual results may differ materially from projections. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice.

Non-banks see surge in commercial lending demand as banks retreat

Findings from Msquared Capital indicate that demand for specialist non-bank lenders is rising as major banks step back from complex commercial lending scenarios. The lender says it is seeing a sharp increase in commercial borrower enquiries heading into 2026 as businesses refinance to manage higher interest rates, address tax obligations and inject fresh working capital.

Written by Julian Barnes – Broker Daily

Msquared Capital general manager of loan origination and credit Michael Volkiene said the trend reflects a broader shift in how commercial borrowers are accessing finance.

“Some lenders are increasingly stepping away from transactions involving complex structures, mixed-use assets or non-standard income,” Volkiene said.

“Borrowers are seeking flexibility and speed, which is driving strong demand for short-term commercial lending solutions.”

New funding strategies

According to Volkiene, new pressure means that many businesses entering 2026 are refinancing not only to secure competitive rates but to restructure their balance sheets and start the year with additional liquidity.

Msquared Capital’s findings come following the    release of new research, which suggests Australian SMEs are facing mounting cash flow pressures. A recent Prospa SME Sentiment Report, conducted with YouGov, found that upcoming Payday Super reforms are expected to tighten already thin working capital buffers for many small businesses, potentially increasing demand for external funding solutions.

From 1 July 2026, employers will be required to pay superannuation at the same time as wages rather than quarterly, changing the timing of cash outflows for businesses. The report found that 41 per cent of SMEs are either unaware of the reform or do not fully understand it, while 30 per cent say they are unsure or unprepared to meet the new payment cadence.

Additionally, other surveys have shown that SMEs may be delaying investments, but remain intent on growing this year, and that business and commercial loan    demand has remained robust so far in 2026.

“We’re not seeing businesses retreat – we’re seeing them recalibrate,” Volkiene said.

“Refinancing is increasingly strategic. It’s about certainty and flexibility, particularly where timing matters.”

Complex solutions

The shift comes as mortgage brokers increasingly encounter complex commercial scenarios that may fall outside the appetite of traditional lenders.

Msquared Capital said this has contributed to stronger interest from mortgage aggregators seeking to expand their commercial lending panels with specialist lenders capable of handling more complicated transactions.

“Business loans secured by residential property assets are the easiest to execute. Very few lenders have the experience needed to navigate complex commercial structures quickly or take a practical view on commercial and industrial property assets,” Volkiene said.

“Aggregators are increasingly focused on credibility and execution, not just capital availability.”

Msquared Capital, which provides real estate-backed loans ranging from $500,000 to $50 million, has recorded 30 per cent year-on-year growth. The firm  recently joined Connective’s commercial panel.   

Broker demand for non-bank commercial lending options continues to increase.

Connective head of commercial and asset finance Brent Starrenburg said brokers are increasingly dealing with more complex commercial lending scenarios.

“We’re seeing more brokers navigate complex commercial scenarios. Msquared Capital brings strong commercial experience and a practical credit approach, particularly for more complex property transactions,” Starrenburg said.

Volkiene said the growth of the non-bank sector has also seen new entrants emerge to fill gaps left by traditional lenders, increasing the importance of experience when structuring commercial deals.

“Commercial lending is relationship-driven and technically complex. Brokers are reporting long wait times on complex scenarios across providers,” he said.

“In this environment, experience matters – from understanding diverse income streams and non-standard documentation, to taking a commercial approach to valuations.”

Similarly, non-bank lender Bizcap told Broker Daily that SMEs are not borrowing just to grow, but to manage timing gaps created by regulatory reform, labour obligations and tightening commercial terms, pressures which are exposing the limits of traditional, static credit models.

Starrenburg added that brokers are increasingly prioritising certainty of funding and transparent lending terms when selecting commercial lending partners.

Disclaimer:

General information only and does not constitute financial, investment, or legal advice. Msquared Capital’s lending activities are limited to writing loans for business and/or investment purposes only. The consumer protections in the National Credit Code do not apply.

Has Australia Reached the End of the Great Economic Ponzi Scheme?

As rising inflation and a worsening housing crisis puts political heat on the property market, Msquared Capital Co-Founder & Fund Manager Paul Miron breaks down why the Australian economy is unravelling after decades of success. He unpacks the dangerously underestimated consequence Robin Hood politics may have for all Australians.

For decades, Australia has been known as the lucky country. Yet luck is not an economic strategy.

In recent years, structural weaknesses that were once masked by growth have been exposed. Australia is currently the only G12 economy to have resumed tightening monetary policy amid persistent inflation, a signal that the underlying pressures are deeper than many care to admit.

Recent OECD data showed Australia recorded one of the largest declines in real household disposable income per capita among advanced economies. Real wages have lagged inflation for several years, meaning Australians are effectively working more to afford less. On a per-capita basis, national income has stagnated and in some periods, gone backwards.

For a generation, Australia rode an extraordinary wave:

  • A once-in-a-century mining boom driven by China
  • A banking system expanding credit into housing
  • Rapid population growth through migration
  • A property market that rarely corrected


Between 1991 and 2020, Australia avoided recession, one of the longest uninterrupted GDP expansions in modern history. This built enormous wealth on paper. Median household wealth ranks among the highest globally. But much of that wealth is tied to property values, approx 67% of our wealth, which is inflated by leverage and demographic growth.

The economic model has worked so far. But the supply side of the economy has been unable to adapt as it has in the past. Has it reached the breaking point?

The Illusion of Growth

For years, GDP growth and low unemployment were treated as proof of sound economic management. On paper, Australia still ticks those boxes.

But GDP growth driven primarily by population expansion is not the same as productivity growth. When output rises simply because more people are added, living standards do not necessarily improve.

Per capita outcomes tell a different story.

Australia has been absorbing one of the highest net migration rates in the OECD. Historically, the supply side of the economy expanded to accommodate this growth. Today, it appears constrained:

  • Infrastructure projects are competing with residential construction for labour and materials
  • Housing supply is lagging population growth
  • Rental vacancies sit near record lows
  • Construction insolvencies are elevated


We are at or near full employment, yet productivity growth has stalled. Since around 2016, labour productivity growth has averaged close to zero, in some years, negative. That means we are adding hours worked without meaningfully increasing output per hour.

In simple terms, we are running faster but not making any further progress.

Structural pressures converging, before the Middle East war

The Australian economy now faces simultaneous, converging structural challenges that have been brewing for over a decade, and both sides of politics are equally to blame. The uncertainties of war in the Middle East will conveniently provide politicians with an excuse to lay blame for higher inflation, higher interest rates, higher living costs, and energy costs when these issues become more critical and apparent in the coming months.

Record public debt, spending, and inflation are all linked

Australians will wake to a $1 trillion government debt this year. Government spending represents 26% of GDP, the highest it has ever been. Spending has grown faster than tax revenue for over 20 years. The difference has been fuelled by debt.

There has been no better economist in our history than the late Milton Friedman, whose life’s work was to understand better inflation, famous for saying, “The only way to finance government spending without taxes is by creating money, and that produces inflation.”

We need to appreciate that the RBA is independent, and its instrument to control inflation is interest rates; however, the other equation in our economy is fiscal spending.

It is exceptionally rare for an ex-RBA governor to comment that “Government handouts have contributed to higher interest rates,” call out the government, and provide such open criticism of government spending, resulting in higher interest rates, weaker wage growth, and slower economic growth.

So where Is the “Ponzi”?

The uncomfortable question is whether Australia’s economic model has relied too heavily on three reinforcing forces:

  1. Rising property values
  2. Expanding credit
  3. Population growth


When asset prices rise, households feel wealthier. They borrow more. Banks lend more. Governments collect more stamp duty and GST. Migration adds demand. GDP grows. Confidence builds.

But if productivity stalls, and debt continues to expand faster than real income, the system becomes increasingly dependent on continual growth in asset values and population inflows to sustain itself.

That dynamic begins to resemble something fragile.

Not a fraud — but a structure that requires constant expansion to remain stable.

Housing supply vs demand

The National Housing Accord sets a target of 1.2 million homes over five years (240,000 per year).

However, ABS Building Activity data show annual dwelling completions currently below that level, at just under 184,000. With building approvals falling further, the issue will only be exacerbated over the longer term.
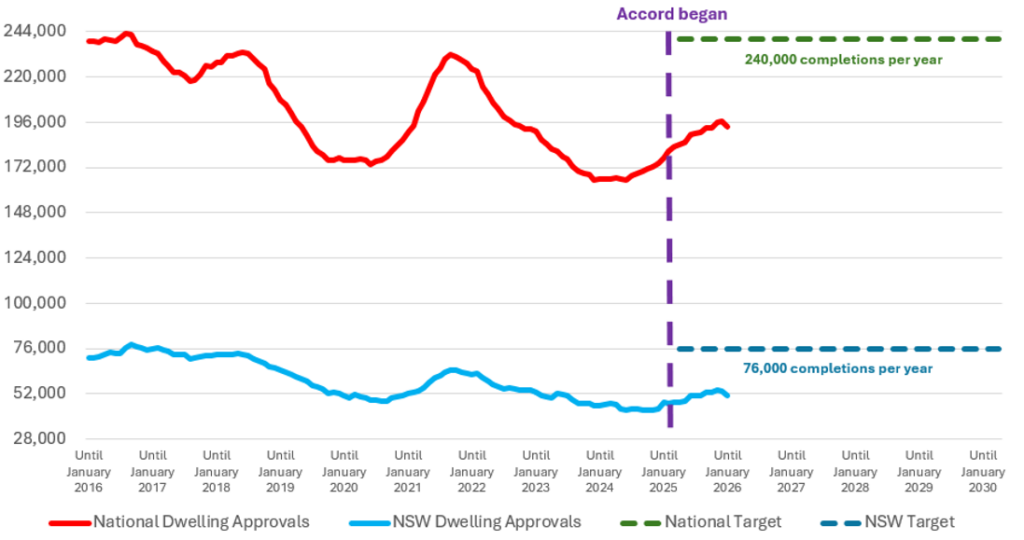
 

Source: Urban Taskforce based on ABS data released 3/3/26

Meanwhile:

  • Rental vacancy rates are near record lows (CoreLogic / SQM Research).
  • Construction insolvencies have risen sharply (ASIC insolvency statistics).


Record infrastructure spending (federal and state) has exceeded $120 billion in pipeline projects nationally (Infrastructure Australia), competing directly with residential construction for skilled labour and materials, which is contributing to housing construction inflation of well over 5% pa.

But it is a model that requires perpetual expansion to maintain stability.

The latest CPI data shows housing as one of the largest contributors to inflation. In January, housing costs rose approximately 6.8% year-on-year, driven by rents, construction costs and utilities.

The private sector is responsible for generating this, comprising an army of mum-and-dad property investors and developers, as well as institutional-sized developers. With construction costs being so high, red tape, and high land values, the numbers at present do not stack up. The result is that the growth corridor areas where supply is supposed to be delivered via decades of infrastructure and planning are not feasible, with more projects stalled until it becomes profitable, the only mechanism available being higher property prices.

CGT discounts and negative gearing

We recently had a 3-day Senate enquiry, listening to economists, on the relationship between high property prices, affordability, and the stability of our housing market.

There is no doubt that tax incentives have contributed to property values over the past two decades, drawing additional demand from property investors; however, the flip side is that without these incentives, fewer properties would have been delivered. Sometimes we need to accept that we cannot fix the problem retrospectively.

The government is seeking to raise further taxes to plug the hole in our budget. My concern is that removing incentives for private sector development will exacerbate the housing crisis further. As an unintended consequence, property prices may go down in the very short term, but then artificially inflate as the supply shortage deepens.

In this scenario, we can expect higher inflation, particularly as rental property supply dwindles and our growth relies on sustaining high levels of migration. Not to mention, it undermines people’s aspirations to work hard and build wealth, since property has long been a tangible, straightforward way to build wealth.

The optics of Robin Hood politics look great, but economically, we all end up suffering if we exacerbate the housing crisis.

Keep in mind that 71% of property investors have one property; these are not ultra-rich people, but regular, hardworking Australians who managed to save enough money to buy an investment property.

It seems reasonable to do the opposite

From an economic perspective, it seems reasonable to provide incentives to increase the supply of property and attract much-needed capital investment.

As we enter a new economic phase, Australia’s future prosperity will not come from rising property prices or population growth alone. It will be both economically and politically suicidal to drastically interfere with the property market. Therefore, I believe property will remain stable, with private credit given a strong foundation to remain a solid and reliable asset class, as long as the manager maintains a high level of discipline.

Our prosperity will come from producing more value per person, not simply adding more people or more debt to the system.

The question is not whether the lucky country can remain prosperous.

The real question is whether Australia can transition from a model built on expansion to one built on productivity, innovation, and sustainable growth.

Disclaimer:

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. Information contained in this article is general in nature and has been prepared without taking into account your objectives, financial situation or needs. It does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice. Property and private credit investments carry risks, including market downturns and borrower defaults, and neither past performance nor security over property guarantees future returns or capital protection.
Top-tier commercial lender Msquared Capital joins Connective commercial panel

Following unprecedented growth in commercial lending demand, Connective has added Msquared Capital to its panel to bolster options for brokers servicing complex commercial lending scenarios.

Specialising in short-term loans, the private credit firm has been added to provide up to 80% LVR lending against residential, commercial and industrial securities.

Msquared Capital was founded in 2017 by former brokers and bankers who specialise in commercial lending. The firm now helps brokers service this growing and diverse segment.

Msquared Capital built its strong reputation on its very high repeat borrower rate, and responsive team of lender BDMs, who take a commercial approach to solving challenging lending scenarios.

Welcoming its addition to the Connective panel, Msquared Capital noted a growing wave of mortgage brokers looking to diversify their businesses into commercial lending.

Msquared Capital General Manager Loan Origination & Credit Michael Volkiene said: “Heading into 2026, many SME’s are in expansion mode or are looking to rebalance how debt sits on their balance sheet. For brokers, this represents a long-term partnership creation opportunity.”

“Lending against a property portfolio is a smart lever that brokers can pull to help commercial borrowers meet their business goals.”

Msquared Capital provides real estate-backed loans from $500,000 up to $50 million for commercial borrowers. It says its experience in a specialised lending arena often helps brokers save borrowers time – and prevent unnecessary expense.

“The commercial lending market is growing rapidly on its own. At the same time, major banks are continuing to tighten their lending criteria, which means we are seeing demand from borrowers in the non-bank space surge. But brokers should be mindful of inexperienced lenders looking to fill the gap.”

Being built for brokers by brokers, Mr Volkiene said Msquared Capital is an experienced partner and this experience is critical in meeting the complex needs of SME’s.

Msquared Capital noted commercial borrowers may have diverse income streams, non-standard documents – and that valuations can often be an expensive pain point.

Msquared Capital has one of the largest valuation panels available on the market, and given its depth of experience, can take a commercial approach to property valuations.

Mr Volkiene said: “Brokers refer their best clients to Msquared Capital, because they know we look after their relationships and help them keep a client for life. We exist to provide certain capital on clear terms.

“We understand that commercial lending is a relationship driven space. Many of the brokers who refinanced their borrower with us in the lead up to Christmas cited concerns over hidden fees from other lenders.

“Our national team of lender BDM’s are excited to support brokers with their commercial lending scenarios in the coming months, whether it be structuring the best solution for clients, or helping brokers understand the costs upfront,” he concluded.

Disclaimer:

General information only and does not constitute financial, investment, or legal advice. Msquared Capital’s lending activities are limited to writing loans for business and/or investment purposes only. The consumer protections in the National Credit Code do not apply.


The lucky country hits a property wall

Property is Australia’s fountain of wealth. Attempts to solve the inflation crisis, such as the proposal to remove CGT, may have unintended consequences, warns Msquared Capital Co‑Founder and Fund Manager Paul Miron.

In an interview with Ausbiz, Paul says that solving the housing crisis requires a sharper focus on incentives for developers. High construction costs, labour shortages driven by major infrastructure projects, and migration levels that far exceed new housing supply are all constraining the market. Without meaningful policy support to bring new projects to market, the imbalance between supply and demand will persist.

Inflation crisis in numbers

  • Inflation 3.8% driving interest rates up to 3.85%
  • Up to 67% of Australian wealth is held in property, well above 50% OECD average
  • Shortfall of 60,000 – 100,000 dwellings per year increasing inflation
  • February inflation data saw housing the dominant inflationary force; a +6.8% house price increase, +32.2% electricity bill increase, and low vacancy rates driving rents higher.

Disclaimer

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. The information provided is general in nature and reflects the views of the speaker at the time of recording. Forward-looking information is inherently uncertain, and actual results may differ materially from projections. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice. Property and private credit investments carry risks, including market downturns and borrower defaults, and neither past performance nor security over property guarantees future returns or capital protection.
Ausbiz: Private credit risks rise as rate hikes loom

With inflation running hot, questions are emerging about how a new rate‑hiking cycle could affect property prices and private credit in the year ahead.

Co-founder & Fund Manager Paul Miron spoke with Ausbiz about the growing risks within parts of the construction sector, cautioning that the property market at an aggregate level can behave very differently to what’s happening on the ground. He explains why unit supply is now commanding his attention. A risk to watch in 2026 and beyond? The impact of rising inflation and higher rates on future unit supply in Australia’s most stretched capital cities.

Key points:

  • Interest rate hikes may stall property price growth and reduce borrowing capacity.
  • Private credit exposed to higher risks, especially in construction and development.
  • Significant undersupply in the national unit market may worsen if rising rates and inflation hamstring developers.
  • 8% forecast rise in property prices is unlikely if borrowing costs climb, with reduced cash flow hampering buyers’ ability to secure finance.
  • Msquared Capital is currently focused on completed property. Careful selection of conservative, defensive private credit deals will remain essential for navigating increased volatility.
Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. The information provided is general in nature and reflects the views of the speaker at the time of recording. Forward-looking information is inherently uncertain, and actual results may differ materially from projections. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice.

Ausbiz: FOMO strikes again for Aussie wealth

A negative change to property prices could have a substantial effect on the economy – the wealth effect – and how much consumers will spend. Co-founder and fund manager Paul Miron gleans lessons from 2025’s gold rush in hindsight – and looks at why property investors should heed these rules of investing heading into 2026.

The interview with Ausbiz covers:

  • Will an RBA holding pattern keep the economy stable?
  • Why APRA is telling you not to buy property
  • 2026 property market expectations

Web disclaimer:

Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293. The information provided is general in nature and reflects the views of the speaker at the time of recording. Forward-looking information is inherently uncertain, and actual results may differ materially from projections. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Before making any investment decision, you should consider whether the information is appropriate to your circumstances and seek independent financial advice.

M2-Logo
Investor Portal

You are about to be redirected to our registry service provider. Do you wish to proceed?

Contact

(02) 9157 8608
[email protected]
Level 12, 88 Pitt Street
Sydney NSW 2000

Please note the following information has been prepared for the use of Wholesale and Professional investors only*. By clicking Agree, you are confirming you are an Australian Wholesale Investor as defined by section 761G of the Corporation Act 2001.

Please note the following information has been prepared for the use of Wholesale and Professional investors only*. By clicking Agree, you are confirming you are an Australian Wholesale Investor as defined by section 761G of the Corporation Act 2001.

We use cookies to improve your experience.