Part 1: The economy — it’s dependency,
The most important slide of the night wasn’t about interest rates. It was about age.
Australia’s dependency ratio, the number of young and old people relative to those of working age, fell from the early 1970s until 2010. For forty years, the workforce grew faster than the population it supported. That meant excess supply, falling inflation and falling interest rates. It was the tailwind behind almost every asset price in our lifetimes.2
That tailwind has turned. Dependency has been rising since 2010, and this year the first baby boomers turn 80. Total population is a proxy for demand; the working-age population is a proxy for supply. As dependency rises, demand grows faster than the capacity to meet it. It shows up as labour shortages. Job vacancies are still around 40% above 2019 levels.2
Immigration does not solve this at the level of the whole economy. Migrants fill vacancies, but they also bring demand: they need homes, services and infrastructure. That is why population growth of 1.4% feels so different in a housing shortage.
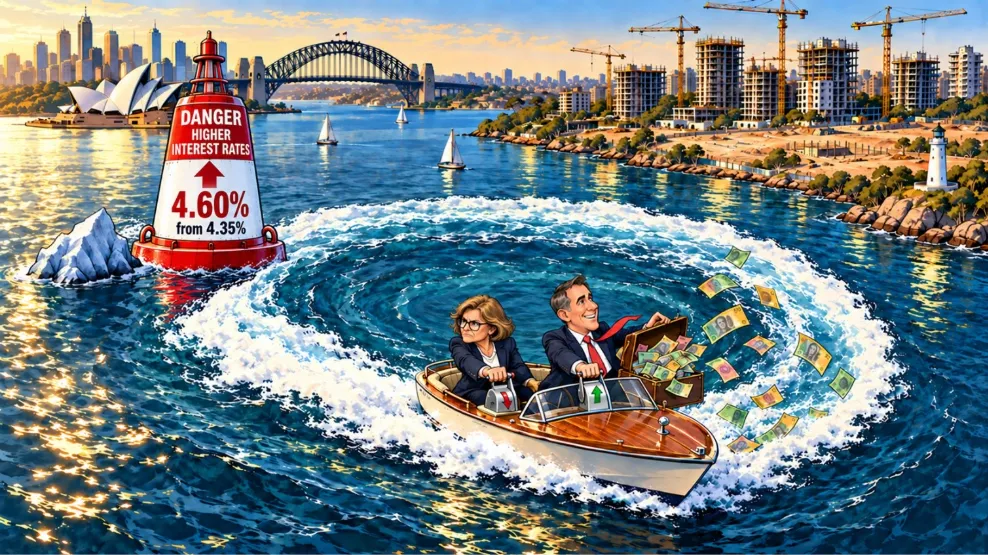
The second force is government. Government consumption spending across all levels now takes around 23% of GDP, up from about 19% a decade ago. And governments plan to grow that spending by around 3% in FY27, while the economy’s speed limit is about 2%. Warren’s arithmetic is simple: to get inflation down, the RBA needs 18–24 months of growth below 2%, and if government takes its 3%, the private sector can barely grow at all. The RBA is pressing the brake while Canberra presses the accelerator.2,3

The third force is AI. Research cited by Warren estimates that a quarter of Australia’s workforce is in roles at high risk of displacement, and more than half will be significantly affected. In the long run, AI may be the productivity answer Australia desperately needs. In the short run, data centres compete with housing for land, power, tradespeople and capital.4
Put the three together and you get Warren’s two uncomfortable realities. Labour is scarcer, so it costs more. Capital is in demand from ageing societies, deficit-funded governments and a global AI investment boom, so it costs more too. Australia’s 10-year bond yield has hit a 15-year high of around 5.4%, and the US 30-year yield reached a 20-year high in August.2
The RBA today lifted the cash rate for the fourth time this year, to 4.60% p.a. Warren’s central case has it above 5% by early 2027, with further hikes in November and February. His reason: after inflation, the real cash rate is barely above zero. For an economy running at its speed limit, that is not restrictive enough.5,2
The RBA is also telling us how much pain it is prepared to accept. Unemployment rose to 4.6% in August, up from 4.5% in July. A week ago, Governor Michele Bullock said that unemployment “between 4.5 and 5 (per cent) will probably take enough heat out of the labour market” to ease inflation. In other words, the RBA expects, and is prepared to accept, a softer jobs market. That matters for property: interest rates create pressure, but unemployment creates forced sellers.6,7
Headline GDP will keep growing, helped by population. But when the population grows at 1.% and the economy at 1.5% (currently trending 2.1%) being the base RBA forecast, GDP per person is barely moving. That is what “going through the motions” looks like.2