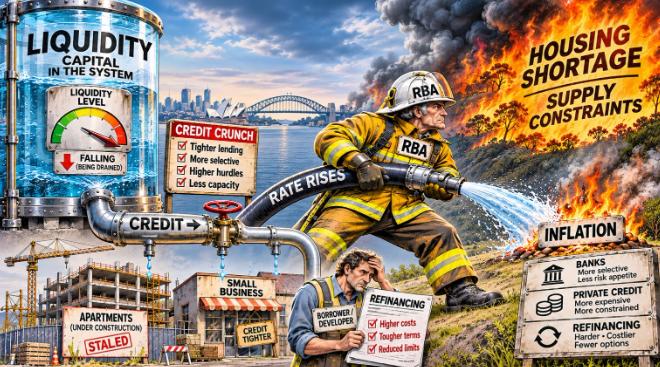
The RBA’s inflation dilemma: fighting inflation today, starving housing supply and Small Business tomorrow.
Australia is in a credit crunch, not the kind most people remember from the GFC. No bank has collapsed, and no funding market has frozen. Money is still out there. What’s gone is the risk appetite.
Lenders are pickier, refinancing takes longer and costs more, and borrowers who assumed they could roll into the next loan are finding the next lender isn’t there. I call it a soft credit crunch.
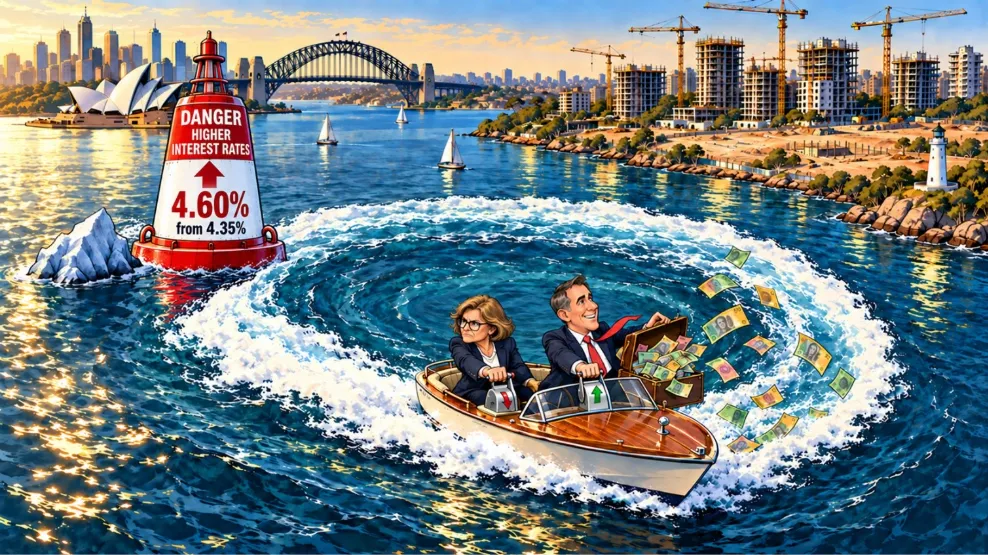
The collapse of Bathla Group into administration, a nervous bond market and the withdrawn Firmus IPO are all symptoms of the same shift in sentiment. Now the Reserve Bank has raised the cash rate for the fifth time this year to 4.85%, and the property and credit cycles are turning together.
Here’s what worries me. Rate rises are meant to cool demand, but this economy’s biggest problem is supply. Higher rates make new developments harder to fund, squeeze small businesses and, over time, mean fewer homes get built. We may be fighting today’s inflation by creating tomorrow’s.
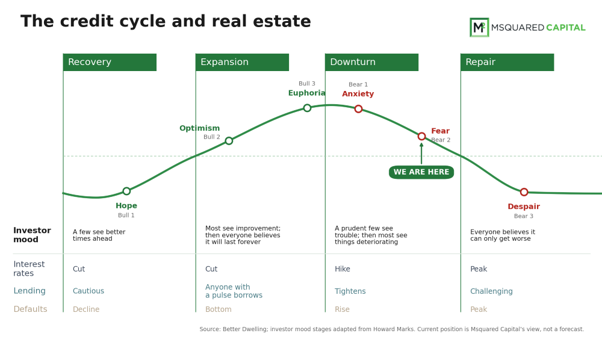
The credit cycle Howard Marks warned about
Few people understand credit cycles better than Howard Marks, co-founder of Oaktree Capital Management. I’ve read his memos for years, and more than two decades ago he described a pattern that keeps repeating: prosperity encourages lending, competition erodes standards, losses follow, and lenders pull back.
That’s where we are. Years of cheap money and a flood of capital into private credit pushed some managers to chase deployment over discipline. As Marks put it in his April 2026 memo on private credit, some direct lenders “accepted too much money and invested it too fast”.
His other point matters as much: cycles are driven by people, not just numbers. Investors ignore risk on the way up and overreact on the way down, sometimes pulling money from perfectly sound deals.
A credit crunch doesn’t mean money disappears. It means lenders stop offering it on yesterday’s terms. That’s the soft credit crunch: the capital is still there; it just isn’t flowing freely.
What has changed at the lending desk
Lenders now want more equity, lower loan-to-value ratios and tighter covenants, and they’re valuing security on today’s prices, not last year’s. Loans written in the good times are maturing into a very different market. The borrowers in trouble aren’t necessarily the ones with poor assets; they’re the ones whose repayment plan depends on finding another lender. A refinance is only an exit if the next lender is there. Good borrowers with a clear way out can still get money, at a price. Projects whose numbers no longer stack up can’t. Much of this pressure also points to an inflation problem that interest rates alone can’t fix.
What has changed at the lending desk
The Reserve Bank is in a bind. Interest rates are a blunt tool: they work by making borrowing dearer and choking off spending. But much of our inflation comes from the supply side, above all housing, along with government charges and costs that barely respond to rate rises.
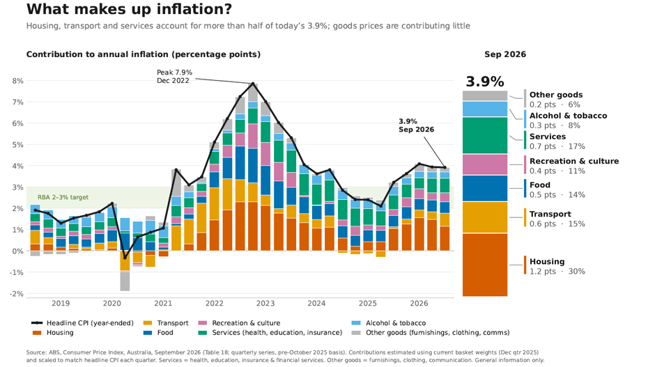
Headline inflation hit 4.3% in the year to September. Housing was the biggest contributor, up 5.2%, driven by rents, new dwelling costs, council rates and electricity.
Oil gets much of the political blame, and fuel is part of the story. Petrol prices are up almost 24% over the year, and transport added close to a percentage point to September’s headline rate, second only to housing. But the oil shock is showing up in headline inflation far more than in the underlying measure. When Russia invaded Ukraine, Brent crude averaged about US$100 a barrel in 2022, and underlying inflation peaked at 6.8%. Brent has been even higher in recent weeks, averaging around US$124 in October, yet underlying inflation is 3.7%. Rate rises can’t bring down the global price of oil, and the largest single contributor to the domestic inflation that remains is housing, the one area where higher rates make the problem worse.
Two oil shocks, very different inflation: underlying inflation vs Brent crude oil
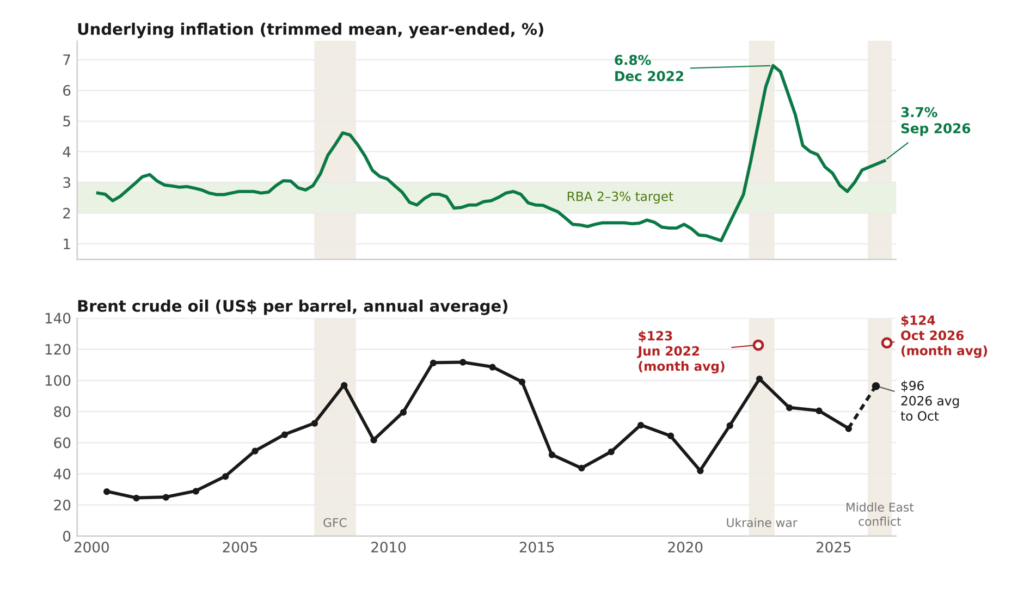
Source: ABS / RBA trimmed mean, quarterly year-ended (2021–2026 from published releases; earlier years approximate); EIA Brent annual averages; 2025–26 monthly averages via countryeconomy.com. Shaded columns mark oil shocks; green band is the RBA’s 2–3% target.
Some of this will ease as demand slows. But no rate rise has ever released more land, sped up a planning approval, made a builder more productive or added a single dwelling. By raising finance costs and killing project feasibility, higher rates can actually make the housing shortage worse.
None of this means the RBA should ignore inflation. It can’t. But monetary policy is carrying too much of the load, and government plays a big part.
Public demand is now close to 29% of the economy, against a pre-pandemic average of about 23.5%. Government spending doesn’t slow when rates go up, so the Reserve Bank has to lean harder on everyone who responds: mortgage holders, businesses that rely on credit, and developers trying to add housing. Every level of government has also added to costs through taxes, charges, red tape and policies that hold back productivity.
Rates clearly have a role in fighting inflation. My concern is that leaning on them alone, without tackling supply and public spending, delivers more economic pain for less and less benefit. We risk winning today’s inflation fight by starving the housing supply we need to win tomorrow’s.
Property: from two speeds to one direction
You can already see the effects in property. The Melbourne Cup Day rise took the cash rate from 4.60% to 4.85%, the fifth increase this year and the highest level since 2008. It wasn’t unanimous: three of the nine board members wanted to hold. The RBA concedes that growth is slowing, property prices are falling, and unemployment is rising, yet it still expects inflation to stay above target until late 2027.
The market was already absorbing the first four rises. National dwelling values fell 1.2% in October, the seventh monthly fall in a row, and are now about 6.7% below the March peak. What looked like a two-speed correction is becoming a national one. In October, Brisbane fell 2.0%, Perth 1.7%, Sydney 1.6% and Melbourne 0.8%.
From two speeds to one: monthly dwelling value change by capital city
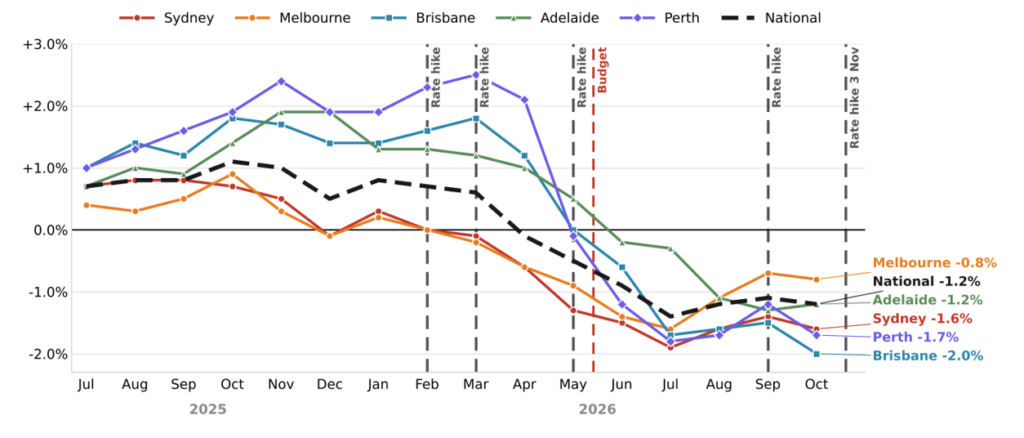
Source: Cotality Home Value Index, monthly % change. October 2026 from the 2 November 2026 release; earlier months from the 1 October 2026 release and may have been revised since. Dashed lines mark RBA cash rate rises (3 Feb, 17 Mar, 5 May, 29 Sep and 3 Nov 2026) and the Federal Budget (12 May 2026).
Sydney is now more than 10% below its February peak, and Melbourne is close to 8% below its November 2025 high. Sales volumes, auction clearance rates and consumer sentiment have all weakened, and as usual they turned first: clearance rates have been stuck below 50% since mid-year, and sentiment fell to 80.4 in October.
This matters well beyond house prices. Falling valuations mean lenders advance less, borrowers need more equity, and projects that worked a year ago no longer get funded. The property cycle and the credit cycle start feeding each other.
Where the opportunity lies
In my view, every credit cycle eventually creates opportunity for investors who can tell the difference between falling prices and failing fundamentals. The best openings rarely come when credit is cheap, and competition squeezes returns. They come when capital gets choosy, values reset, and borrowers have to compete for funding.
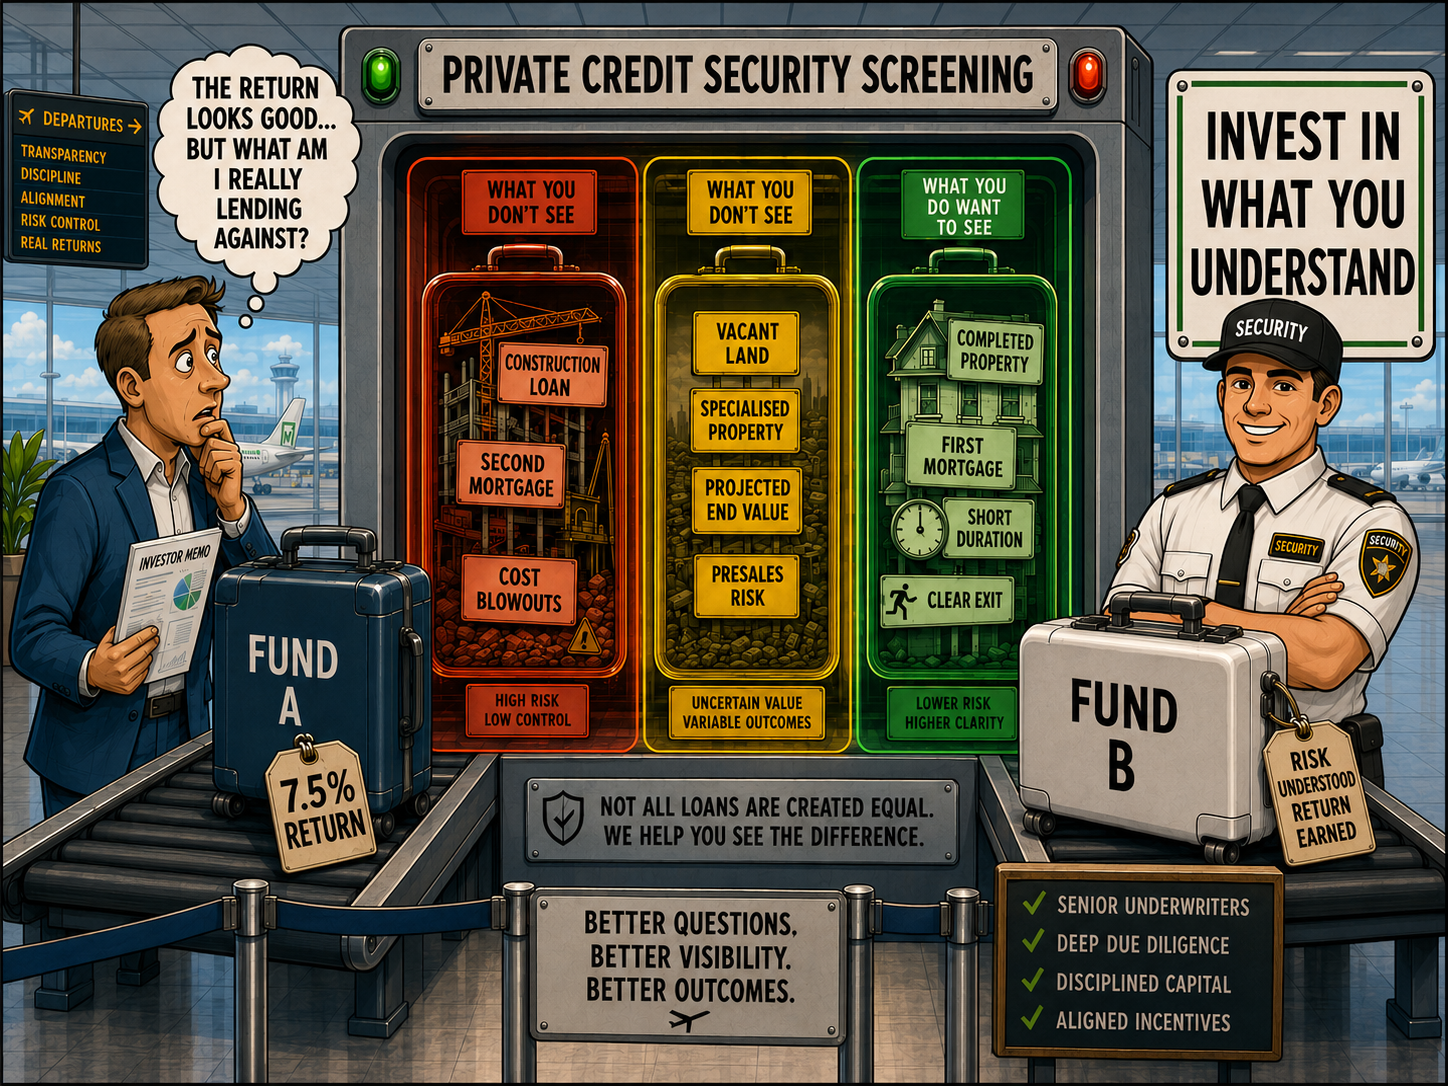
That doesn’t mean you should try to pick the bottom. Nobody can, which is why patience is worth so much right now. In private credit, tighter conditions mean better pricing, lower leverage and stronger protections for lenders. But the same conditions put pressure on loans already written: falling valuations and harder refinancing raise the risk of defaults, delays and losses, and investors in private credit funds can be exposed to those losses and to limits on withdrawals. But a higher yield isn’t the same as a better investment. What counts is asset quality, a realistic valuation, a sound balance sheet, and a credible way out.
At this point in the cycle, the difference between lenders shows up less in the returns they advertise than in how disciplined they behaved through the cycle: what they lent against, how much, and on what terms. Capital that waits indefinitely can miss the reset, and capital that rushes in because rates have risen can be caught by it. What matters is the flexibility to act when risk and reward line up.
How the cycle ends
Property corrections and credit crunches don’t end at the same time. A property correction starts to settle once lower prices bring buyers back. A credit crunch ends only when lenders regain confidence, balance sheets are repaired, and capital is willing to take risk again. That usually takes a lot longer.
For more than a decade, low rates, plentiful liquidity and rising government spending let leverage build and asset prices climb. Now the market is unwinding those excesses. Borrowers will have to cut debt, add more equity, or sell. Some projects won’t go ahead, business investment will be curtailed, and some lenders will take losses on decisions made in the good times.
Joseph Schumpeter called it creative destruction: capital moving from weaker hands to more productive ones. It hurts, but it’s how markets restore discipline.
Policymakers will be tempted to step in whenever it gets painful. Too much intervention drags out the imbalances the market is trying to fix. The real test is telling necessary market discipline apart from damage caused by policy failures.
As Marks reminds us, cycles are inevitable; what matters is how you behave through them. The lenders who come out strongest won’t be the ones who lent the most in the boom. They’ll be the ones who cared about security and underwriting before the cycle turned. And the investors best placed for the next upswing will be those who stayed patient, managed risk and recognised when sentiment had gone too far to take the opportunity.
The era of cheap money rewarded leverage. The next era will reward discipline.
Important information
Msquared Capital Pty Ltd ACN 622 507 297 AFSL 520293.
The information provided is general in nature and reflects the views of the author at the time of publication. The information has been prepared without taking into account your objectives, financial situation or needs, and does not constitute personal financial product advice, investment advice or a recommendation. Opinions and forward-looking statements are inherently uncertain and may not prove correct. Third-party data is drawn from the sources cited and has not been independently verified, and reference to or quotation of any third party does not imply that party’s affiliation with, or endorsement of, Msquared Capital.
Not an offer to invest. Investments in funds managed by the Msquared Capital group are not bank deposits, may be illiquid, and the performance of those funds, return of capital or payment of distributions are not guaranteed. Before making any investment decision, you should consider whether the information is appropriate having regard to your objectives, financial situation and needs, read the relevant fund disclosure documents, and seek independent financial advice.
Sources
- ABS, CPI rose 4.3% in the year to September 2026, media release, 28 October 2026.
- ABS National Accounts, June quarter 2026 (via Queensland Treasury summary, 2 September 2026); MacroBusiness / IFM Investors, public demand share of GDP, February and June 2026.
- IMF World Economic Outlook, October 2026, as reported by The New Daily, 13 October 2026.
- AIHW, Home ownership and housing tenure (2021 Census).
- Bank forecasts (CBA, NAB, Westpac, ANZ, 28 October 2026) and ASX RBA Rate Tracker (29 October 2026 close), via Property Investment Professionals, 31 October 2026. Repayment and borrowing-capacity figures are illustrative estimates from the same source.
- Cotality Home Value Index and auction clearance rates (2 November 2026 release); Westpac–Melbourne Institute Consumer Sentiment Index.
- Bloomberg, Australian private credit hit by big banks’ retreat, October 2026.
- Howard Marks, Oaktree Capital memo “What’s Going on in Private Credit?” (9 April 2026) https://www.oaktreecapital.com/insights/memo/whats-going-on-in-private-credit9. Reserve Bank of Australia, Statement by the Monetary Policy Board: Monetary Policy Decision, 3 November 2026.
- EIA Brent crude annual averages; countryeconomy.com Brent monthly averages, 2025–26; ABS / RBA trimmed mean inflation; ABS CPI contributions by group, September 2026.
- The Urban Developer, Bathla’s $3.4b collapse enters new phase as construction shuts down, 25 September 2026. https://www.theurbandeveloper.com/articles/bathla-update-construction-shut-down
- ABC News, Data centre operator Firmus pulls blockbuster ASX float after lacklustre demand, 9 October 2026, https://www.abc.net.au/news/2026-10-09/firmus-float-gets-pulled-following-lacklustre-investor-demand/107246230